$dX_t = b(X_t)\,dt + \sigma(X_t)\,dW_t$
Stochastic Analysis
Itô calculus, stochastic differential equations and the behaviour of processes driven by noise.
PhD Student
Department of Mathematics, Imperial College London
PhD Thesis Inference and inverse problems for stochastic interacting particle systems
I work where probability meets partial differential equations. My research centres on stochastic interacting particle systems: their analysis, their numerical simulation, and how to draw statistical inferences about them from data. Currently funded by CCMI CDT.
Randomness, differential equations, and the computation in between.
Itô calculus, stochastic differential equations and the behaviour of processes driven by noise.
Estimating parameters and quantifying uncertainty in random models from discrete, noisy observations.
Developing data-driven methods for learning, forecasting and uncertainty quantification in systems governed by stochastic dynamics.
Well-posedness, regularity and qualitative behaviour of partial differential equations arising in applications.
Designing and analysing discretisation schemes: convergence, stability and computational cost.
Things I am building and working on.
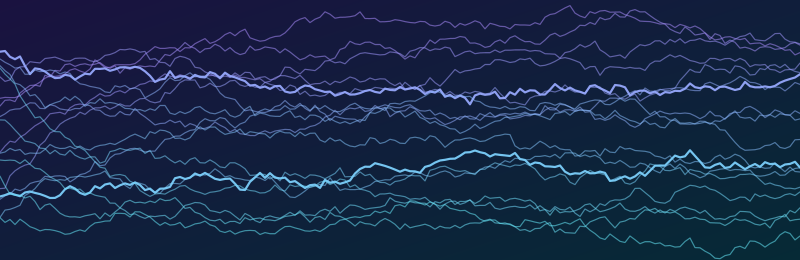
Simulation schemes for stochastic differential equations and stochastic PDEs: methods for generating accurate sample paths of systems driven by noise.